Term Plan in India: Benefits, Premium, Coverage, Riders and Tax Rules
A term plan is one of the simplest ways to protect your family's financial future. It provides life insurance coverage for a specified period in exchange for premiums paid according to the policy terms. If the insured person dies during the policy term and the claim is admissible, the insurer pays the death benefit to the nominee or other eligible claimant.
Unlike investment-linked insurance products, a standard pure term plan primarily focuses on financial protection rather than wealth creation. Understanding coverage requirements, premium calculations, exclusions and tax rules can help you make an informed decision.
What Is a Term Plan?
A term plan is a type of life insurance that provides financial protection for a defined period, such as 20, 30 or 40 years, subject to the insurer's available options and eligibility conditions.
For example, a 30-year-old earning ₹12 lakh annually may purchase a term plan with ₹1 crore of life cover for a period extending to age 60 or 65. If the insured person dies during the covered period and the claim is valid, the nominee receives the applicable death benefit.
In a standard pure term plan, there is generally no maturity payout if the insured person survives until the policy expires. Return-of-premium variants may offer a maturity benefit under specified conditions, but their premiums are typically higher.
How Does a Term Plan Work?
The process generally involves the following steps:
- Choose the coverage amount: Estimate your family's future financial requirements, outstanding loans and other liabilities.
- Select the policy term: Align the coverage period with your major financial responsibilities.
- Complete the application: Provide accurate information about your age, income, occupation, medical history, smoking status and existing insurance.
- Pay the premium: Pay according to the selected payment frequency and policy conditions.
- Nominate a beneficiary: Identify the nominee and keep the nomination details updated.
- Claim the benefit when necessary: Following the insured person's death, the claimant submits the required documents for assessment by the insurer.
Policy issuance, premium rates, underwriting requirements and claim eligibility depend on the insurer's terms and applicable regulations.
Key Benefits of a Term Plan
1. Financial protection for your family
The death benefit can help dependants manage regular living expenses, repay outstanding loans and continue important financial goals.
2. High life cover relative to premium
Pure term insurance generally offers a substantial life cover for a comparatively lower premium than many life insurance products that combine protection with savings. Actual premiums depend on age, health, lifestyle, policy duration and other underwriting factors.
3. Flexible policy duration
The policy term can be selected according to your financial responsibilities. Someone with young children and a long outstanding home loan may need protection for longer than someone whose dependants are financially independent.
4. Optional riders and additional benefits
Some insurers offer riders or additional policy features, such as accidental death benefits, critical illness cover or waiver of premium. These may increase the premium and are subject to specific terms and eligibility requirements.
5. Possible tax advantages
Eligible life insurance premiums may qualify for deductions under Section 80C of the Income-tax Act, 1961, subject to the applicable conditions and tax regime. Qualifying death benefits are generally exempt under Section 10(10D), subject to statutory requirements.
Tax treatment should be checked against the rules applicable to the relevant financial year.
How Much Term Insurance Cover Do You Need?
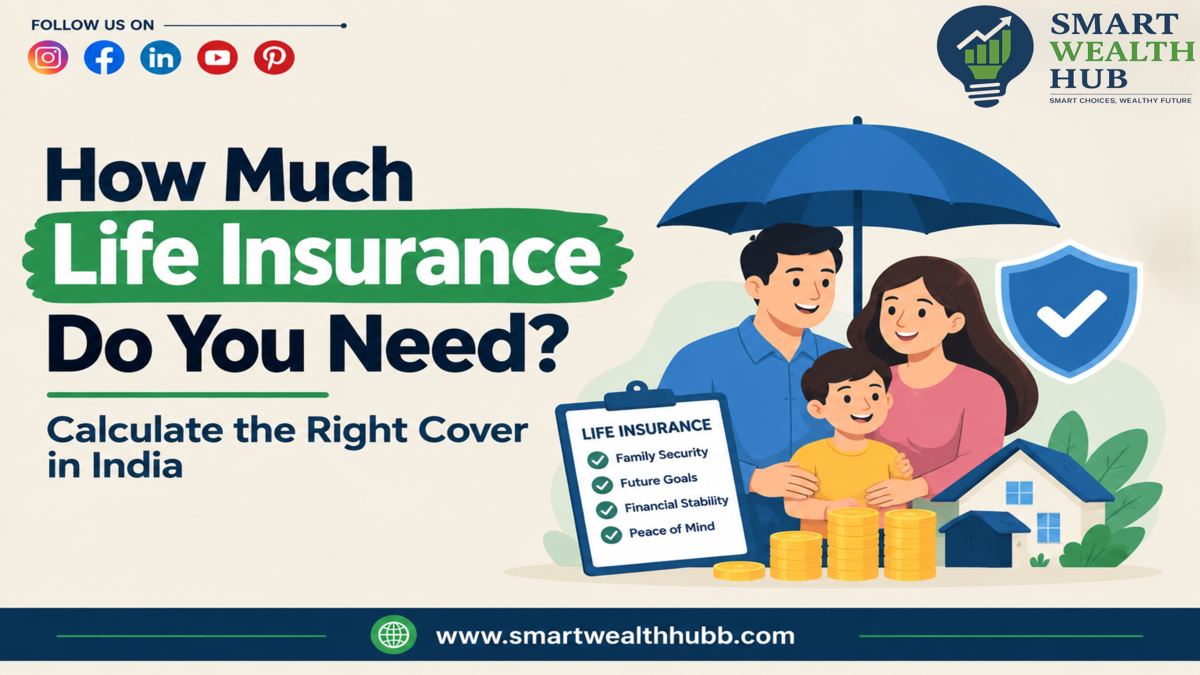
There is no single life-cover amount suitable for everyone. Your requirement depends on your family's expenses, liabilities, financial goals, existing assets and other sources of income.
A practical starting point is:
Required cover = Outstanding liabilities + Future family needs + Financial goals − Existing assets available for those needs
Consider this illustrative example:
| Financial requirement | Estimated amount |
|---|---|
| Outstanding home loan | ₹35 lakh |
| Other liabilities | ₹5 lakh |
| Family living expenses | ₹60 lakh |
| Children's education goals | ₹20 lakh |
| Immediate and other financial needs | ₹5 lakh |
| Total financial requirements | ₹1.25 crore |
| Less: Existing liquid savings available for these goals | ₹15 lakh |
| Less: Existing suitable life insurance cover | ₹10 lakh |
| Estimated additional life cover required | ₹1 crore |
This example assumes the living-expense requirement and other goals have already been estimated in today's money or appropriately adjusted for inflation. Avoid deducting assets that your family cannot realistically access or that are already earmarked for another goal.
A more detailed calculation should account for inflation, future income requirements, existing investments, dependants' ages and other income sources.
Why inflation matters when calculating life cover
Money required in the future may be substantially greater than the amount required today.
Suppose a household currently spends ₹60,000 per month. If expenses rise by an illustrative 4% annually, the projected monthly expense after 20 years would be:
Future expense = Current expense × (1 + inflation rate)ⁿ
₹60,000 × (1.04)²⁰ ≈ ₹1,31,467 per month.
That means monthly expenses could rise from ₹60,000 to approximately ₹1.31 lakh after 20 years at this assumed inflation rate.
This is an illustration, not a forecast. Actual inflation may be higher or lower. The purpose is to demonstrate why life cover calculations should account for the future purchasing power of money.
You should also avoid counting the same financial goal twice. For a more complete assessment, use a life-cover calculator if one is available from a reliable provider, or work through your household's liabilities, expenses and existing resources systematically.
Explore the Financial Planning Guide for your financial planning needs and access the Term Insurance Calculator to estimate your required life insurance coverage.
How Is a Term Plan Premium Calculated?
Insurers assess several factors before determining the premium:
- Age: Premiums are generally lower when a person buys cover at a younger age, assuming comparable underwriting conditions.
- Health: Medical history, existing conditions and relevant test results may affect underwriting.
- Smoking and tobacco use: These can materially affect premiums and eligibility.
- Sum assured: Higher cover generally costs more.
- Policy term: The duration of protection influences the premium.
- Occupation and lifestyle: Certain occupational or recreational risks may affect underwriting.
- Policy features and riders: Additional benefits may increase the total premium.
Illustrative premium calculation
Assume a hypothetical applicant receives the following annual premium quotation for a pure term plan:
| Component | Illustrative annual premium |
|---|---|
| Base term plan with ₹1 crore cover | ₹12,000 |
| Accidental death benefit rider | ₹1,500 |
| Critical illness rider | ₹2,500 |
| Waiver of premium rider | ₹500 |
| Total annual premium with all three riders | ₹16,500 |
These figures are illustrative only, not actual market rates or a quotation from an insurer. They do not establish that all three riders can be purchased together under one policy. Availability, pricing, taxes, eligibility and underwriting requirements vary by insurer and product.
The difference is:
- Base-plan premium: ₹12,000 per year.
- Premium with selected riders: ₹16,500 per year.
- Additional annual cost: ₹4,500.
- Increase over the base premium: ₹4,500 ÷ ₹12,000 × 100 = 37.5%.
Over 20 years, assuming the premiums remain unchanged and the policy continues under the same terms, the simple total would be ₹2.4 lakh for the base plan versus ₹3.3 lakh with the selected riders—a difference of ₹90,000. This calculation excludes taxes, discounts, premium changes, policy changes and the time value of money.
Before choosing riders, compare the extra cost with the specific financial risk they cover.
Term Plan Add-ons: What Riders Can You Consider?
A rider is an additional contractual benefit attached to a policy when offered by the insurer. Some benefits may instead be included in the base policy or offered as a separate insurance product.
Not every rider is available with every term plan. Names, definitions, eligibility conditions, exclusions, payout structures and limits differ between insurers.
Choosing the right add-ons can help address financial risks that a basic term plan may not fully cover.
1. Accidental Death Benefit Rider
An accidental death benefit rider may provide an additional payout if the insured person dies due to an accident covered under the rider's terms.
Example: Suppose a policyholder has ₹1 crore of basic life cover and an accidental death benefit rider providing an additional ₹25 lakh. If the insured dies in a covered accident and all claim conditions are satisfied, the total benefit could be ₹1.25 crore.
Who may consider it? People whose occupations or regular activities involve greater exposure to accidental risks, subject to the rider's eligibility conditions.
What to check: Covered events, exclusions, the definition of accidental death, rider expiry age and whether the benefit is paid in addition to the base sum assured.
2. Accidental Total and Permanent Disability Rider
This rider may provide a lump-sum benefit or periodic payments if the insured suffers a qualifying total and permanent disability caused by an accident.
Such a disability may prevent the policyholder from earning an income, creating financial pressure even when the insured survives.
Who may consider it? Individuals whose families depend heavily on their earnings.
What to check: The policy's definition of total and permanent disability, qualifying causes, medical assessment requirements, waiting periods where applicable and whether partial disability is covered.
Do not assume every disability or inability to work qualifies for a payout.
3. Critical Illness Rider
A critical illness rider may pay a lump sum if the insured is diagnosed with a specified illness and meets the policy's definition and claim conditions.
Depending on the policy, covered conditions may include certain cancers, heart attacks, strokes or other serious illnesses.
The payout may help meet treatment-related expenses, household costs or loan repayments during recovery. However, it is not a substitute for comprehensive health insurance.
Who may consider it? People who want additional financial protection against the potential income disruption associated with specified serious illnesses.
What to check: The list and definitions of covered illnesses, survival period if applicable, waiting period, exclusions, severity criteria and whether the rider terminates after a claim.
4. Waiver of Premium Rider
A waiver of premium rider may waive future premiums for the eligible policy when a specified event occurs, such as a qualifying disability or covered critical illness.
This can help prevent the policy from lapsing because the policyholder cannot afford premiums during a difficult period.
Example: If a policyholder becomes eligible for a waiver under the rider's conditions, future premiums covered by the waiver may no longer need to be paid for the specified period. The life cover can continue according to the contract.
Who may consider it? Individuals who want to protect the continuity of their life insurance if they experience a qualifying event.
What to check: The triggering event, definition of disability or illness, duration of the waiver and whether the rider covers only the base policy or eligible additional benefits as well.
5. Terminal Illness Benefit
Some term plans include a terminal illness benefit, while others offer it as an optional feature. It may allow the policyholder to receive some or all of the applicable death benefit following diagnosis of a terminal illness that meets the policy's definition.
This can help with financial planning during a serious illness. However, receiving an early payout may reduce the amount subsequently payable to the nominee.
Who may consider it? Policyholders who want to understand whether their life cover provides financial support during a qualifying terminal illness.
What to check: Whether the benefit is included automatically or offered separately, the medical definition, payout limits, documentation requirements and the effect on the remaining death benefit.
6. Income Benefit Rider
An income benefit option may provide regular payments to the nominee or beneficiary after the insured person's death instead of, or in combination with, a lump-sum payout, depending on the product design.
Regular payments can help a family manage monthly household expenses and maintain financial stability.
Who may consider it? Families who prefer structured income support rather than managing a large lump-sum payment themselves.
What to check: Payment frequency, duration, whether payments increase over time, the total benefit payable and whether the option is a rider or an alternative death-benefit payout structure.
7. Increasing Life Cover Option
Some insurers offer an increasing-cover feature that raises the sum assured over time according to specified rules. This may help address inflation and growing financial responsibilities.
For example, a policy with an initial cover of ₹1 crore could offer an increase under a contractual schedule. The actual amount and timing depend on the product; the increase should not be assumed to follow a particular percentage unless the policy specifies it.
Who may consider it? People expecting their financial responsibilities to increase over time, such as those with young children or a growing home loan.
What to check: The increase schedule, premium adjustments, maximum cover, eligibility conditions and whether increases are automatic or optional.
How to Choose the Right Term Plan Add-Ons
Not every rider is necessary for every policyholder. Before selecting one, consider the following:
- Identify your main financial risk: Consider income loss, accidental death, disability or the financial impact of a specified critical illness.
- Check existing coverage: Review any employer-provided insurance, personal accident policy, disability benefits and health insurance to avoid unnecessary duplication.
- Compare the additional premium: Evaluate the cost of each rider against the specific protection it offers.
- Read the exclusions carefully: Understand definitions, waiting periods, survival periods, claim limits and other conditions.
- Review claim requirements: Check the documentation and medical evidence required to establish eligibility.
- Confirm policy compatibility: Some riders may be available only with selected plans or within specific age and sum-assured limits.
A useful approach is to prioritise adequate base life cover first, then add riders that address meaningful gaps in your existing financial protection.
Important: Rider benefits, exclusions, eligibility requirements and payout structures vary by insurer and product. Some benefits described above may be included in the base policy rather than offered as separate add-ons. Review the policy wording and benefit illustration before purchasing any rider.
The final two items may be policy features or payout structures rather than separate riders. Confirm their classification in the insurer's policy documents.
Base term plan vs. term plan with riders
| Feature | Base term plan | Term plan with selected riders |
|---|---|---|
| Main purpose | Death-benefit protection | Death-benefit protection plus specified additional risks |
| Premium | Generally lower | Generally higher |
| Accidental death | Only if covered by the base policy's terms | Additional benefit may be available through a rider |
| Critical illness | Not automatically covered | May be covered through an eligible rider |
| Disability-related support | Depends on base policy | May be available through a qualifying rider |
| Complexity | Usually simpler | Requires review of additional definitions, limits and exclusions |
| Best selection principle | Choose adequate life cover first | Add only benefits that address genuine protection gaps |
Worked example: How much difference can riders make?
Consider a hypothetical 30-year-old applicant who is comparing a ₹1 crore base term plan with the same cover plus selected riders.
- Base plan: ₹12,000 annually.
- Selected riders: ₹4,500 annually.
- Total with riders: ₹16,500 annually.
- Additional cost: ₹375 per month on an annualised basis.
The ₹375 monthly equivalent is calculated by dividing the additional annual cost of ₹4,500 by 12. It is not necessarily the monthly instalment an insurer would offer.
The decision should not be based only on the additional premium. For example, a critical illness rider may cover only a specified list of illnesses and may have survival periods, waiting periods, exclusions or severity requirements. An accidental death rider does not necessarily pay for every death involving an accident; its contractual definition and exclusions apply.
Read the policy wording and compare the rider's benefit with existing employer insurance, personal health insurance, disability protection and emergency savings.
Tax Benefits of Term Insurance in India
Tax treatment depends on the law in force, the financial year, the policy's terms and the taxpayer's circumstances.
Under the earlier Income-tax Act, 1961, eligible life insurance premiums could qualify for a deduction under Section 80C, subject to its conditions and the combined annual limit of ₹1.5 lakh. This deduction was generally relevant under the old tax regime rather than the new regime.
India's Income-tax Act, 2025 took effect from 1 April 2026. For financial years beginning on or after that date, taxpayers should verify the corresponding provisions, eligibility requirements and section references under the new legislation rather than automatically relying on section numbers from the earlier Act.
Life insurance death benefits have generally been eligible for exemption when the applicable statutory conditions are met. However, the tax treatment of maturity proceeds, surrender proceeds and other payouts may differ according to the policy and applicable law.
Before making a tax decision:
- Check the tax regime applicable to you.
- Verify the current provisions for the relevant financial year.
- Review premium-payment and policy conditions.
- Consult a qualified tax professional if your circumstances are complex.
Do not buy insurance solely for a tax deduction. The primary purpose of a term plan is financial protection.
Important Exclusions and Policy Conditions
A term plan is subject to the contract's terms. Before buying, check:
- The policy's suicide clause and applicable conditions.
- Exclusions and limitations associated with each rider.
- Waiting periods, survival periods and qualifying definitions where relevant.
- Medical disclosure requirements and the consequences of material non-disclosure.
- Premium-payment deadlines and consequences of a lapsed policy.
- Claim documentation and the insurer's claims process.
- Whether the cover is level, increasing or structured to reduce over time.
Provide accurate information about health, tobacco use, occupation and medical history when applying. Incomplete or incorrect disclosures can create claim complications.
Read the policy document, customer information sheet and applicable rider wording before accepting the policy.
How to Choose a Suitable Term Plan
Use the following checklist before making a decision:
- Estimate your family's financial needs and outstanding liabilities.
- Account for inflation, future goals and existing assets.
- Select a policy term that covers your key financial responsibilities.
- Compare premiums, exclusions, underwriting requirements and claim conditions.
- Review the insurer's policy wording and applicable disclosures.
- Assess riders individually instead of selecting every available add-on.
- Check tax treatment under the legislation and tax regime applicable to you.
- Review your cover when you marry, have children, take on significant debt or experience a major change in income.
Refer to our Retirement Planning Guide to plan for a financially secure retirement. To determine the right life insurance coverage for your needs, use our Life Insurance Calculator.
IRDAI Regulations and Important Policy Conditions
Life insurers in India are regulated by the Insurance Regulatory and Development Authority of India (IRDAI). Policyholders should review the applicable regulatory framework and the specific policy wording before purchasing cover.
Accurate disclosures
Provide complete and truthful information about medical conditions, smoking or tobacco use, occupation, income and existing insurance. Incomplete or inaccurate disclosures can lead to disputes and may affect claim decisions under the applicable law and policy terms.
Nomination and beneficiary details
Check that the nominee's details are correct and updated after major life events. Make sure your family knows how to locate the policy document and contact the insurer.
Free-look period
Eligible life insurance policies generally provide a 30-day free-look period from receipt of the policy document, subject to applicable regulations and conditions. Review the policy promptly and follow the insurer's prescribed process if you wish to cancel during this period.
Premium payments and lapse conditions
Understand the premium due dates, applicable grace period and consequences of non-payment. Do not assume that missing a payment will leave the policy unaffected.
Exclusions and riders
Review the policy wording for exclusions, rider limitations, claim requirements and other conditions. An additional rider may increase the premium and may have terms different from those of the main policy.
Claim settlement process
The insurer assesses claims under the policy contract and applicable law. Keep the policy number, insurer contact details and relevant documents accessible to your nominee.
For official regulatory and policyholder information, visit the IRDAI website and its Policyholder Education and Protection portal. Consult the actual policy wording for the conditions applicable to your coverage.
Common Mistakes to Avoid When Buying a Term Plan
- Choosing insufficient cover: Base your decision on financial responsibilities and dependants' needs rather than a convenient premium.
- Selecting an unsuitable policy term: Coverage may expire while dependants still rely on your income or significant liabilities remain.
- Hiding medical information: Inaccurate disclosures can complicate underwriting and claim assessment.
- Ignoring the full policy wording: A low premium does not automatically mean better value. Review exclusions, optional benefits, payment conditions and claim procedures.
- Overlooking inflation: A fixed sum assured may have less purchasing power in the future. Consider whether an available increasing-cover option or a higher initial sum assured better matches your needs.
- Treating insurance as an investment: A pure term plan is primarily a protection product. Evaluate insurance needs separately from investment and wealth-building goals.
Conclusion
A term plan can provide essential financial protection for dependants if the insured person dies during the policy term. The right policy depends on the amount of cover required, affordability, duration, health and the family's financial responsibilities.
Start by choosing adequate base life cover. Then assess whether riders such as accidental death benefit, critical illness cover or waiver of premium address risks not adequately covered elsewhere. Compare the additional premium with the actual benefit, exclusions and eligibility requirements.
No policy or rider should be selected on the basis of promotional claims alone. Review the contractual terms, verify current tax provisions and choose protection that fits your needs and budget.
Frequently Asked Questions
What is a term plan?
A term plan is life insurance that provides financial protection for a specified period. If the insured dies during the policy term and the claim is payable under the contract, the nominee receives the applicable death benefit.
How much term insurance cover should I buy?
Estimate outstanding debts, future household expenses and financial goals, then subtract assets available for those needs. Account for inflation, existing insurance and other household income before choosing the final cover.
Are term insurance riders worth buying?
Riders can be useful when they address a specific financial risk that is not adequately covered elsewhere. Their value depends on the additional premium, benefit definitions, exclusions and eligibility conditions.
Can I get tax benefits from a term plan?
Eligible premiums and policy proceeds may receive tax benefits, subject to the applicable legislation, tax regime and policy conditions. Because India's Income-tax Act, 2025 took effect on 1 April 2026, verify the provisions applicable to the relevant financial year.
Does a term plan pay money if I survive the policy term?
A standard pure term plan generally does not pay a maturity benefit if the insured survives the policy term. Some products offer different payout structures, so check the policy wording rather than assuming all term plans work identically.
These articles are for awareness. For advice suited to your goals, talk to our team.
Book a free consultationDisclaimer: Views in this article are for educational purposes and do not constitute personalised financial, tax, or investment advice. Markets involve risk — read all related documents carefully.

Comments0
No comments yet. Be the first to share a thought.